Raising Money Smart Kids: A Parent’s Guide to Financial Education
Parents teach children countless skills as they grow, from tying their shoes to making responsible decisions. Money is another important part of that education. Raising money smart kids does not require complicated financial lessons or long conversations about investing. It starts with everyday experiences that help children understand what money is, where it comes from, and how thoughtful choices affect what they can do with it.
For families in North Brookfield, MA, and surrounding communities, conversations about money can become part of normal family life. The goal is not to expect children to understand every financial concept at once, but to gradually build knowledge and confidence as they get older.
Why Teaching Kids About Money Is More Important Than Ever
Children see money being used every day, but seeing a transaction does not necessarily teach them how money works. They may understand that a parent uses a card to buy groceries without realizing that the purchase still involves money coming from a bank account.
Teaching financial concepts early gives children opportunities to practice making decisions before they become responsible for larger financial choices themselves. Parents can use ordinary situations to introduce concepts such as:
- Needs & Wants: Help children understand the difference between something they need and something they simply want.
- Saving: Explain that setting money aside can help them afford something they want in the future.
- Spending: Let children make age-appropriate purchasing decisions and experience the results of those choices.
- Planning: Show how having a goal can make it easier to decide how much money to save or spend.
- Responsibility: Explain that money decisions have consequences, both positive and negative.
These lessons can create a foundation for more advanced conversations about checking accounts, credit, borrowing, and budgeting as children mature.
Building a Strong Financial Foundation in Early Childhood
Young children do not need complicated financial terminology. They can start learning through simple activities that connect money to familiar experiences.
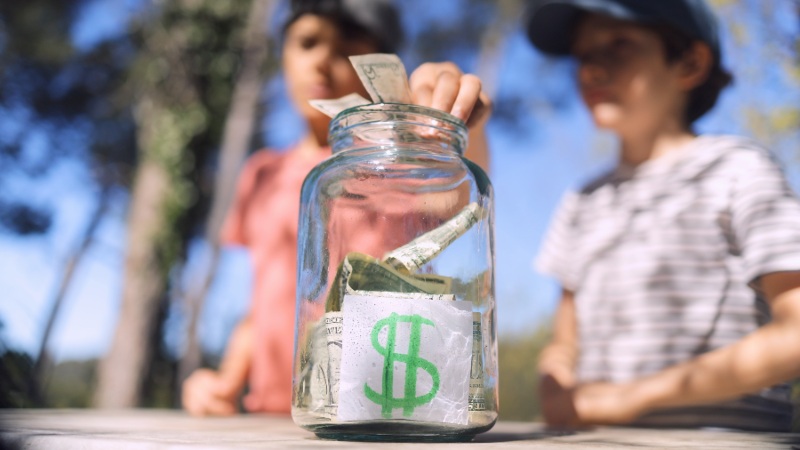
For example, parents can give children a small allowance for completing age-appropriate responsibilities. Rather than simply telling a child to save, parents can provide separate containers for money that will be saved and money that can be spent. This makes an otherwise abstract concept visible.
Shopping trips can also become learning opportunities. If a child wants a particular toy, help them understand that buying it means using money that could otherwise be saved for something else. This introduces the idea of making choices without turning every purchase into a lecture.
Children can also learn that money is earned through work. Parents can explain, in simple terms, how adults earn income and use that income to pay for housing, food, transportation, and other expenses.
The goal at this stage is bringing up money smart kids who understand that money is a limited resource that requires choices.
Teaching Pre-Teens Smart Money Habits
As children become more independent, financial lessons can become more detailed. Pre-teens may be ready to manage a larger allowance, earn money through age-appropriate work, or save toward more expensive purchases.
This is a good time to introduce basic budgeting. A child who receives $20, for example, can decide how much to spend now and how much to save for a future goal. Parents can help them think through the decision rather than making the decision for them.
Pre-teens can also learn about comparison shopping. If they want a particular product, encourage them to look at different prices and consider whether the purchase is worth the cost. Other useful lessons include:
- Goal Setting: Encourage children to establish specific savings goals.
- Budgeting: Help them plan how they will divide available money between spending and saving.
- Comparison Shopping: Teach them to consider price, quality, and usefulness before purchasing.
- Delayed Gratification: Explain that waiting to buy something can sometimes lead to a better decision.
- Giving: If it fits your family’s values, let children decide whether they want to dedicate part of their money to helping others.
These experiences allow children to practice financial decision-making while the consequences are still relatively small.
Preparing Teenagers for Financial Independence
Teenagers are approaching financial decisions that can have much greater consequences. They may be preparing for college, purchasing a first vehicle, getting a job, or opening a bank account.
This is the time to expand conversations about money beyond saving and spending. Teenagers can begin learning about checking accounts, debit cards, credit, interest, borrowing, and the importance of reviewing account activity.
Parents can also explain the difference between income and take-home pay. A teenager with a first job may be surprised that the amount received in a paycheck is different from the amount earned before deductions.
Budgeting becomes especially useful at this stage. A teenager can create a basic monthly budget that accounts for income, regular expenses, savings, and discretionary spending.
Conversations about credit are also important. Teenagers should understand that borrowing money creates an obligation to repay it and that making payments as agreed can affect their credit history.
Practical Ways Parents Can Model Smart Financial Behavior
Children learn from what parents say, but they also learn from what parents do. Parents who want to raise money smart kids can make everyday financial decisions part of the learning process.
That does not mean sharing every detail of your household finances. Instead, parents can explain appropriate decisions in simple terms.
For example, when comparing two products, explain why you chose one over another. When planning for a major purchase, explain that saving beforehand can make the expense easier to manage. When reviewing a household budget, demonstrate how different expenses fit into an overall plan.
Parents can also make financial conversations routine rather than treating money as a taboo subject. The more comfortable children become asking questions, the more opportunities parents have to correct misunderstandings and introduce new concepts.
Common Mistakes to Avoid When Bringing Up Money Smart Kids
Financial education does not have to be perfect. However, parents can make the process more effective by avoiding a few common mistakes.
One mistake is waiting until children are teenagers to discuss money. Younger children can begin learning basic concepts through everyday activities.
Another mistake is making every conversation about restrictions. If children only hear that they cannot afford something, they may associate money with anxiety rather than seeing it as a tool for making choices.
Parents should also avoid making financial decisions entirely on behalf of older children. Teenagers need opportunities to make manageable mistakes and learn from them before they are responsible for larger financial commitments.
Finally, avoid assuming that one conversation is enough. Financial education is an ongoing process. What a six-year-old needs to know about money will be different from what a sixteen-year-old needs to understand.
Building Financial Confidence One Lesson at a Time
A parent’s guide to raising money smart kids should not be a complicated curriculum. It is a collection of age-appropriate conversations, experiences, and examples that help children gradually understand how money works.
From teaching a young child to save for a desired toy to helping a teenager create a monthly budget, parents can use everyday situations to build financial skills. Families in North Brookfield, MA, can also use their local banking relationships as opportunities to help older children become more familiar with responsible financial habits.
The goal is simple: give children the knowledge and experience they need to make thoughtful financial decisions as they become more independent. Contact our team at North Brookfield Savings Bank to learn more.
Raising Money Smart Kids FAQ
Parents often have questions about when to begin financial education and which lessons matter most. These answers can help provide a starting point for raising money smart kids.
At What Age Should Children Start Learning About Money?
Children can begin learning basic money concepts as soon as they are old enough to understand simple ideas about buying, saving, and making choices. Younger children can learn through activities such as saving coins, using an allowance, or discussing needs and wants.
What Are the Most Important Money Lessons for Kids?
Important lessons include understanding needs versus wants, saving for goals, spending thoughtfully, budgeting, earning money, and understanding that financial choices have consequences. As children grow older, these concepts can expand to include banking, credit, borrowing, and financial planning.
How Can Parents Raise Money Smart Kids?
Parents can teach financial responsibility through age-appropriate conversations and real-life experiences. Allow children to make manageable decisions about saving and spending, explain financial choices when appropriate, and model thoughtful financial behavior in everyday life.